Life Right
Life Right: An Honest Guide to the Pros and Cons
A growing number of South Africans are considering a Life Right.
Life Right ownership enables you to invest in a lifestyle that offers security, peace of mind and a number of included amenities, without the capital and financial commitments that come with purchasing property.
1. Why do people love a Life Right?
A Life Right becomes an increasingly attractive option when you don’t have the capital or don’t want to commit to purchase a property. As people begin to live longer, they start to look for a more cost-effective alternative that can cater to their care needs. When you consider a Life Right, you can be assured of all-inclusive accommodation with the added benefit of assisted living and frail care as you age.
2. What exactly is a Life Right?
A Life Right enables you to buy the right to use the accommodation unit for the rest of your life. When the Life Right agreement includes couples, the right to use the unit ends only when the second spouse or partner passes away too. When this happens, the right to use the unit reverts to the owner of the complex who can then resell it. Once the unit has been resold, the deceased’s estate will receive all or a portion of the original purchase price subject to the terms laid out in the original agreement. Some Life Rights can include a refund of the initial investment plus a percentage of the profits on resale, while others provide for the repayment of a percentage of the purchase price subject to inflation.
3. What are the benefits if you own a Life Right?
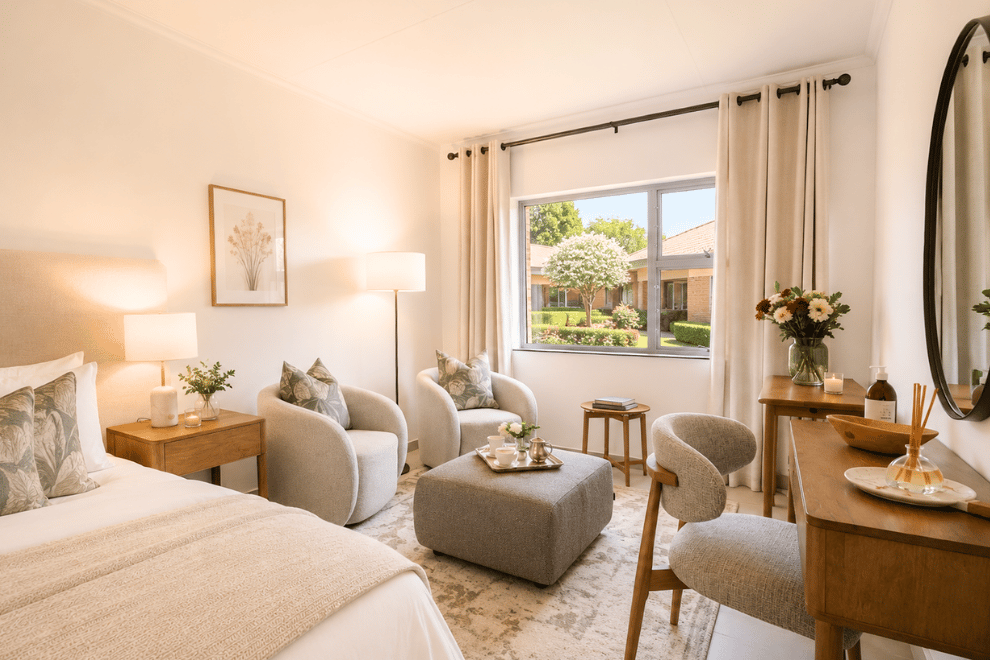
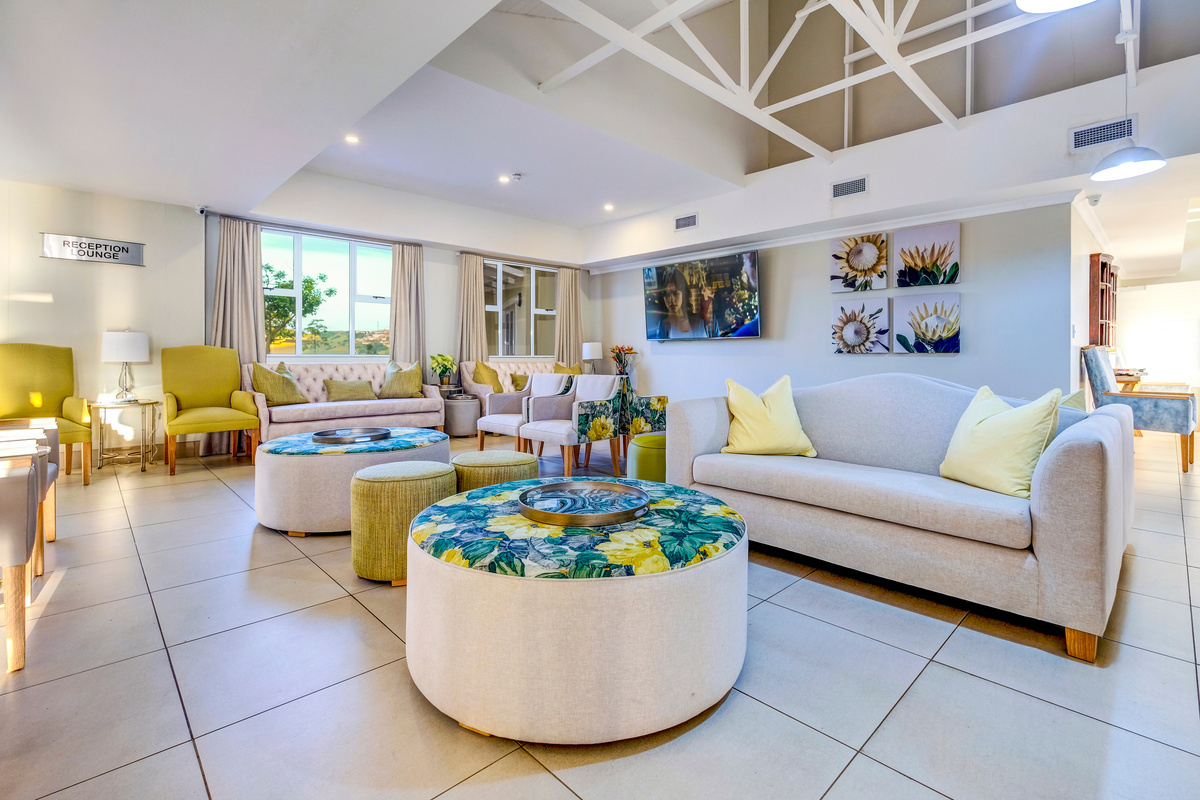
A Life Right is an attractive option because it provides all the advantages of homeownership without having to worry about insurance, home maintenance, housekeeping, and security. Many modern retirement villages offer an all-inclusive experience including meals, activities, medical care and opportunities to socialize, together with stylish accommodation. What’s more, purchasing a Life Right removes the need to pay transfer duties, VAT or bond registration. All of which make it a more affordable option for you. In addition to this, the Life Right holder is given a draft levy budget for the first few years of occupation. This transparency allows you to plan your finances ahead of time without being concerned about any hidden costs later.
4. What are the potential disadvantages if you own a Life Right?
While there are many advantages when you own a Life Right, there are a few considerations that should also be considered. The contract with the developer or care provider will stipulate what portion of the resale value will go to the deceased estate. Adjustments for profit and inflation will also be considered. There may in some cases be limitations as to who may occupy or buy the rights to the property. This could complicate the resale process. Also, if the company that owns the property becomes insolvent and the property needs to be resold, the Life Right holder is also considered a creditor and will be last in line when it comes to redistributing the assets.
As a result, always be sure to check that you are completely happy with the terms before committing to any Life Right agreement. It may be useful to consult with your attorney or financial advisor for complete peace of mind.
Here when you need us
Let us help you find the right support
Receive personal guidance on the living and care options available for you or someone you love.
Request personal guidanceThis article offers general information and does not replace individual medical or dietetic advice.